


 Buying a fixer-upper in Valparaiso can be an attractive way for Veterans to build equity and customize a home to their preferences. VA loans can absolutely be used to purchase homes that need cosmetic updates or minor repairs. Projects like flooring replacement, interior painting, kitchen upgrades, or landscaping improvements typically do not prevent VA financing. This flexibility allows Veterans to consider properties that may need updating while still using their earned benefits.
However, major safety or structural concerns must be addressed before closing. The VA appraisal requires that the home meet minimum property requirements, which focus on safety, soundness, and sanitation. Issues such as roof damage, unsafe electrical systems, active water intrusion, broken heating systems, or other hazards must typically be repaired before the loan can be finalized. Understanding these guidelines prevents surprises during the appraisal process.
Knowing VA repair standards helps Veterans shop wisely and structure offers strategically. A knowledgeable real estate team can help identify potential red flags early and advise whether repairs are manageable within VA guidelines. With proper planning, buying a fixer-upper in Valparaiso using a VA loan can be a smart path to homeownership while protecting long-term investment value.
At Kimberly Sut Group, we are proud to be top realtors near you, serving buyers, sellers, and veterans throughout Lake County, Porter County, Jasper County, Newton County, and LaPorte County. Our business continues to grow because of the trust, support, and referrals from our amazing clients. Whether you’re buying, selling, relocating, or using your VA home loan benefits, our team is honored to be your local real estate resource and grateful for every referral that helps our business grow.
👉What’s My Property Worth? https://www.kimberlysutgroup.com/seller/homeestimate/default
Call or text: (219) 789-1987
Visit our website: https://www.kimberlysutgroup.com
Follow us on Facebook: https://www.facebook.com/Kimberlysutrealestate/


Read our 5-Star Google Reviews: https://g.page/r/CVNvGzCU3UZ3EBM/review

Kimberly Sut Group
Top Realtor for Buyers & Sellers in Northwest Indiana
Specializing in VA Homes, First-Time Home Buyers, Estate Sales & Relocations
 Monticello, Indiana has become a popular destination for Veterans who want to enjoy small-town living paired with recreational opportunities, especially near
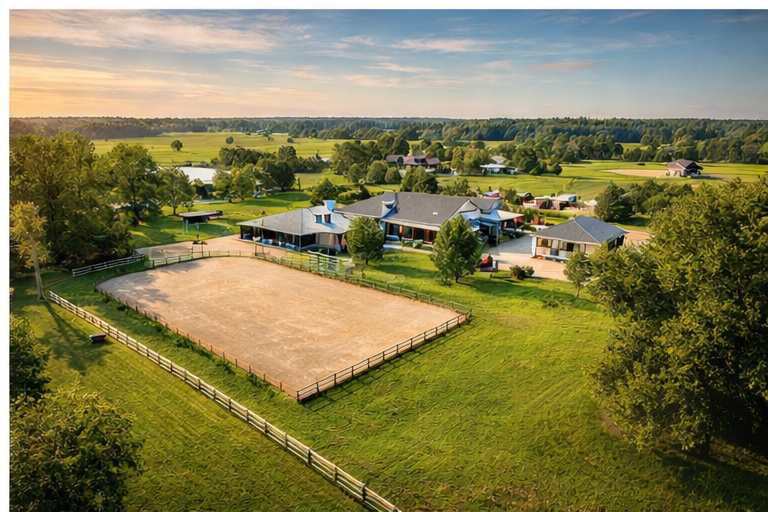 Equestrian properties often take longer to sell than traditional homes—and that’s normal. Horse properties appeal to a smaller, more specialized buyer pool, and buyers typically take extra time evaluating land, zoning, barns, and overall usability.
 VA pre-approval is one of the most important steps a Veteran can take before beginning the home search in Valparaiso. A true pre-approval means a lender has reviewed income, credit, debt, and VA eligibility—not just issued a quick pre-qualification estimate. This documentation shows sellers that financing is already vetted, reducing uncertainty and strengthening the overall offer. In a market where homes can receive multiple offers, certainty matters.
 VA loans offer flexible credit guidelines, but timing still matters. Some Veterans are ready to buy now, especially if their income, savings, and debt levels support approval under current lender standards. Because the VA does not set a strict minimum credit score, many borrowers who may not qualify for conventional financing can still move forward confidently with a VA loan in Valparaiso.
 When an estate property doesn’t sell quickly, executors and heirs often become anxious. Questions start piling up:
 Receiving multiple offers on an estate property can feel like a relief—but it can also create pressure. Executors often worry about choosing the “right” offer and whether their decision could be questioned later by heirs or the court.
 VA disability income can often be used to qualify for a home loan in Valparaiso, depending on lender guidelines and proper documentation. For many Veterans, disability compensation provides stable, tax-free income that may strengthen overall purchasing power. Because VA disability income is typically ongoing and reliable, lenders frequently consider it when calculating debt-to-income ratios and overall loan eligibility.
 Buying a home that allows chickens involves much more than finding a property with a large backyard. Zoning laws determine whether poultry is permitted, how many hens are allowed, whether roosters are prohibited, and where coops can be placed. Setback requirements, minimum lot sizes, and accessory structure rules all factor into whether a property truly supports chicken ownership. Without verifying these details, buyers risk purchasing a home that does not legally align with their plans.


 Veterans deserve more than a transactional real estate experience. Buying a home with VA benefits requires a team that understands VA loan guidelines, military relocation challenges, and long-term planning—not just paperwork and deadlines. That level of understanding is why so many Veterans choose Kimberly Sut Group when purchasing homes in Crown Point, Indiana.