Area Real Estate News & Market Trends

The Kimberly Sut Group Real Estate Blog is your trusted source for buying, selling, and investing in Northwest Indiana real estate. Our posts offer expert advice on the local housing market, first-time homebuyer tips, staging strategies, relocation guides, neighborhood spotlights, and the latest updates on mortgage programs like USDA and VA loans. Whether you’re searching for homes in Valparaiso, Crown Point, Merrillville, Chesterton, Lowell, or the surrounding communities, our blog provides in-depth insights, market trends, and resources to help you make confident real estate decisions.


What Our Real Estate Blog Offers:


  • Local Market Insights – Stay up to date with housing trends, pricing, and new developments across Northwest Indiana.

  • Buyer Guides – Learn how to navigate financing, inspections, first-time buyer programs, and finding the right home for your lifestyle.

  • Seller Resources – From staging and pricing strategies to attracting qualified buyers, we give sellers the tools to sell faster and for top dollar.

  • Relocation & Community Spotlights – Get to know neighborhoods, schools, local businesses, and community highlights to see which area fits you best.

  • Specialty Real Estate – We cover everything from horse properties and luxury homes to estate sales and investment opportunities.

  • Team Expertise – Hear from the Realtors at Kimberly Sut Group about their specialties, client success stories, and personal tips.

Oct. 16, 2026

Porter County Indiana Halloween Events & Trick-or-Treating 2026

Looking for Halloween events and Trick-or-Treating in Porter County, Indiana?

October is packed with family activities throughout Porter County, and we're excited to be part of the fun!

One event to put on your calendar is the annual Trunk or Treat at Sunset Hill Farm County Park in Valparaiso on Saturday, October 17 from 3:00–6:00 PM. Porter County Parks says the event is free, open to kids of all ages, and includes community partners handing out candy and giveaways. Porter County Parks and Recreation

Downtown Valparaiso is also hosting its Downtown Trick-or-Treat Friday, October 23 from 4:00–6:00 PM, with more than 100 local businesses and organizations participating. Valparaiso Events

Then come find us in Hebron!

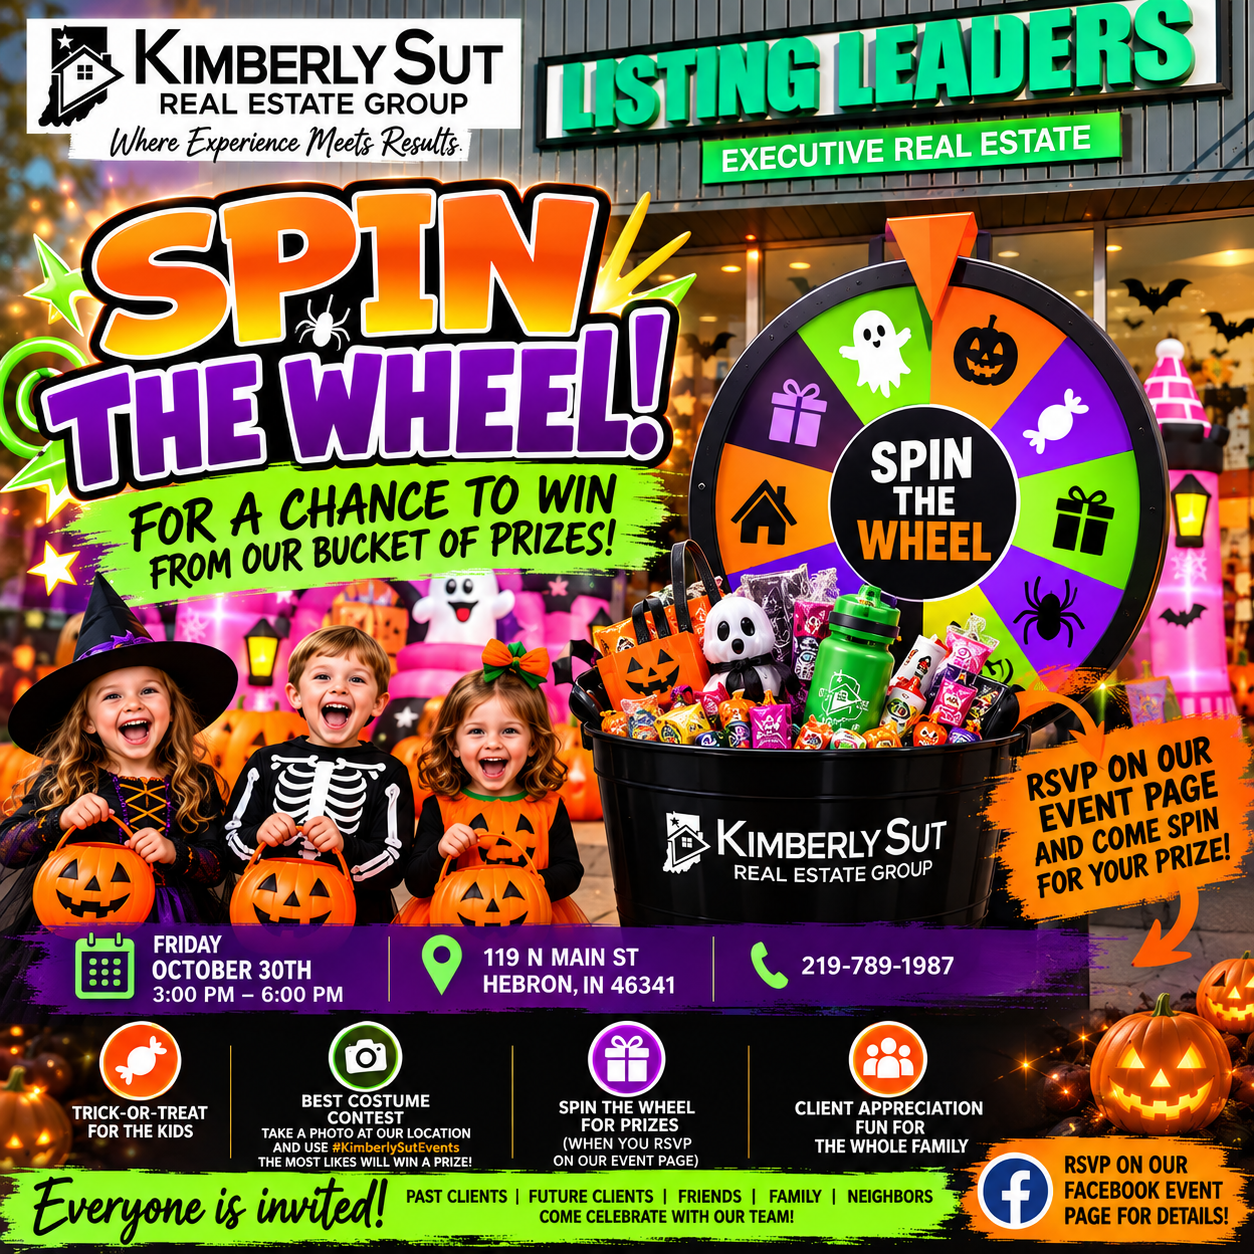
Kimberly Sut Real Estate Group Trick-or-Treat
Friday, October 30, 2026
3:00–6:00 PM
119 N Main St
Hebron, IN 46341
219-789-1987

We'll have treats plus our Best Costume Contest!

Take a photo at our location, post it using #KimberlySutEvents, and the photo with the most likes will win a prize.

Visit Kimberly Sut Real Estate Group

See Our Facebook Event for More Details

Follow us for more surprises along the way!

Posted in Halloween Event
Oct. 16, 2026

VA Loans vs. Conventional Loans: What Veterans Should Compare


When Veterans begin exploring home loan options, the comparison often comes down to VA loans versus conventional loans. While interest rates usually get the most attention, they are only one part of the equation. Veterans should compare the total cost and long-term impact of each loan type—not just the rate.

VA loans are backed by the U.S. Department of Veterans Affairs and are designed to make homeownership more accessible and affordable for eligible Veterans.

Down Payment Requirements

One of the most significant differences between VA and conventional loans is the down payment.

VA loans often allow:

  • $0 down payment for eligible Veterans

  • Greater purchasing power without depleting savings

Conventional loans typically require:

  • 3%–20% down, depending on the program

  • Larger upfront cash investment

Keeping savings intact can be critical for emergencies, transitions, or future goals.

Mortgage Insurance vs. No PMI

Conventional loans with less than 20% down usually require private mortgage insurance (PMI), which increases monthly payments.

VA loans:

  • Do not require PMI

  • Reduce monthly housing costs

  • Improve long-term affordability

Eliminating PMI often saves Veterans hundreds of dollars per month.

Qualification Standards and Flexibility

VA loans are known for flexible qualification guidelines. While the VA does not set a minimum credit score, conventional loans often have stricter credit and debt requirements.

VA underwriting considers:

  • Residual income (money left after expenses)

  • Stable income rather than just credit scores

  • Overall financial picture

This flexibility helps many Veterans qualify more comfortably.

Closing Costs and Fees

VA loans limit certain lender fees and allow seller contributions toward closing costs. Conventional loans may include higher or less regulated fees.

Veterans should compare:

  • Total cash needed at closing

  • Allowable fees and concessions

  • Long-term cost of insurance or financing add-ons

Lower upfront costs often improve long-term outcomes.

Long-Term Cost Comparison Matters Most

Even if a conventional loan appears competitive on interest rate alone, added costs such as PMI, larger down payments, and higher fees can make it more expensive over time.

VA loans frequently offer:

  • Lower monthly payments

  • Faster equity buildup

  • Better long-term affordability

Funding Fee Considerations

VA loans may include a funding fee, which helps support the program. However:

  • It can often be financed into the loan

  • Some Veterans are exempt due to service-connected disabilities

  • The fee may still be less costly than years of PMI

Understanding the full picture helps Veterans make informed decisions.

Final Takeaway

When comparing VA loans to conventional loans, Veterans should look beyond interest rates. Down payments, insurance, qualification flexibility, and total cost all play a role.

In many cases, VA loans provide greater long-term affordability and financial flexibility, making them a powerful option for eligible Veterans seeking sustainable homeownership.

👉What’s My Property Worth? https://www.kimberlysutgroup.com/seller/homeestimate/default

📞 Call or text: (219) 789-1987
🌐 Visit our website: https://www.kimberlysutgroup.com
📘
Follow us on Facebook: https://www.facebook.com/Kimberlysutrealestate/

⭐ Read our 5-Star Google Reviews: https://g.page/r/CVNvGzCU3UZ3EBM/review


Kimberly Sut Group
Top Realtor for Buyers & Sellers in Northwest Indiana
Specializing in VA Homes, First-Time Home Buyers, Estate Sales & Relocations

Posted in Veterans VA
Oct. 14, 2026

What If an Estate Property Is Located in Another County or State?

Many executors discover that the estate property is not located where they live—or even where the probate case is filed. Out-of-county and out-of-state estate properties are common, and while they add complexity, they can absolutely be sold successfully with the right approach.

Probate Location vs. Property Location

Probate is typically opened in the county where the deceased lived, not necessarily where the property is located. This means:

  • The court may be in one county

  • The property may be in another county or state

  • Local rules and procedures may differ

Understanding this distinction helps avoid confusion early.

Authority Still Comes From the Court

Regardless of property location, authority to sell comes from:

  • The probate court

  • Letters testamentary or administration

  • Trust documentation (if applicable)

Once authority is granted, it generally applies across county lines—and sometimes across state lines—with proper documentation.

Out-of-County Estate Property Sales

Selling a property in another Indiana county may involve:

  • Different recording offices

  • Different local market conditions

  • Local buyer expectations

Having a professional familiar with that specific county helps ensure accurate pricing and marketing.

Out-of-State Estate Property Considerations

If the property is in another state, additional steps may be required, such as:

  • Ancillary probate

  • Coordination with out-of-state attorneys

  • State-specific disclosure rules

These sales require careful coordination but are very common.

Managing the Property From a Distance

Distance creates challenges such as:

  • Property access

  • Maintenance

  • Showings

  • Security


Local representation is critical to protect the property and keep the sale moving.

Buyer Confidence Matters More With Distance

Buyers want reassurance that:

  • The seller has authority

  • The property is being managed properly

  • Closing timelines are realistic

Clear communication builds confidence and reduces fallout.

Why Professional Coordination Is Essential

Multi-location estate sales require coordination between:

  • Attorneys

  • Courts

  • Title companies

  • Local real estate professionals

Experience prevents delays and costly mistakes.

Distance Doesn’t Have to Delay the Sale

With proper planning, out-of-county and out-of-state estate properties can sell just as smoothly as local ones. The key is understanding the process and assembling the right team.

Selling an Estate Property From a Distance?


If you’re handling an estate property located outside your county or state, understanding the process early helps protect the estate and reduce stress.

👉What’s My Property Worth? https://www.kimberlysutgroup.com/seller/homeestimate/default

📞 Call or text: (219) 789-1987
🌐 Visit our website: https://www.kimberlysutgroup.com
📘
Follow us on Facebook: https://www.facebook.com/Kimberlysutrealestate/

⭐ Read our 5-Star Google Reviews: https://g.page/r/CVNvGzCU3UZ3EBM/review


Kimberly Sut Group
Top Realtor for Buyers & Sellers in Northwest Indiana
Specializing in VA Homes, First-Time Home Buyers, Estate Sales & Relocations

Posted in Estate Sales
Oct. 14, 2026

RSVP & Spin the Wheel! Prizes at Our Hebron Client Appreciation Event

RSVP. COME SEE US. SPIN THE WHEEL!

We're adding even more fun to our October 30 event.

RSVP on our Facebook Event page, then come visit Kimberly Sut Real Estate Group in Hebron.

When you arrive, you'll have an opportunity to:

SPIN THE WHEEL!

Spin for your chance to win from our bucket of prizes.

It's our way of adding a little extra fun—and saying thank you to the people who continue to support our team.

WHERE TO FIND US

Kimberly Sut Real Estate Group
119 N Main St
Hebron, IN 46341

Friday, October 30
3:00 PM–6:00 PM

Bring the family. Bring the kids. Wear your costumes. Grab some treats.

And make sure you enter our Best Costume Contest.

Take a picture at our location, post it with #KimberlySutEvents, and the photo with the most likes wins a prize!

RSVP on Facebook to Join the Fun

Visit Kimberly Sut Real Estate Group Online

Follow us for more events, giveaways and surprises throughout the year!Spin the Prize Wheel

Posted in Halloween Event
Oct. 14, 2026

Things to Do for Halloween with Kids in Porter County Indiana

October is a great time to get out with the family and enjoy Porter County, Indiana.

If you have little ones who love costumes and candy, there are several dates worth adding to your calendar.

October 17: Porter County Parks' Trunk or Treat at Sunset Hill Farm County Park runs from 3:00–6:00 PM and is free to attend. Porter County Parks and Recreation

October 23: Downtown Valparaiso Trick-or-Treat runs from 4:00–6:00 PM. Organizers say more than 100 businesses and organizations will participate, and the event takes place rain or shine. Valparaiso Events

October 30: Come see Kimberly Sut Real Estate Group in Hebron from 3:00–6:00 PM!

We're located at:

119 N Main St
Hebron, IN 46341

Bring the kids in costume, grab some treats and enter our Best Costume Contest.

Take your photo at our location and use #KimberlySutEvents. The photo with the most likes wins a prize!

Search Homes & Explore Northwest Indiana with Kimberly Sut Real Estate Group

Follow Our Halloween Event on Facebook

And keep following us—there may be more surprises along the way!

Posted in Halloween Event
Oct. 12, 2026

Free Halloween & Trick-or-Treat Events in Porter County Indiana 2026

Halloween fun doesn't have to mean spending a fortune.

Families looking for free Halloween activities in Porter County have several opportunities to get the kids dressed up and out of the house.

Porter County Parks' Trunk or Treat at Sunset Hill Farm County Park is free and takes place October 17 from 3:00–6:00 PM. 

Downtown Valparaiso Trick-or-Treat is another free, kid-friendly event, happening October 23 from 4:00–6:00 PM. 

And don't forget about us!

Come visit Kimberly Sut Real Estate Group in Hebron on October 30 from 3:00–6:00 PM.

119 N Main St
Hebron, IN 46341

Come in costume, get some treats and enter our Best Costume Contest.

Post your photo with #KimberlySutEvents and start collecting likes. The photo with the most likes will win a prize!

Kimberly Sut Real Estate Group

See Our Facebook Event

Follow us for more surprises along the way!

Posted in Halloween Event
Oct. 12, 2026

Buying a Home After Military Service: What Veterans Should Know


Transitioning from military service to civilian life brings many changes—new careers, new routines, and new financial decisions. One of the biggest choices many Veterans face is whether and when to buy a home. When used strategically, VA home loan benefits can provide stability, long-term equity, and a strong foundation for the next chapter of life.

VA home loans are administered by the U.S. Department of Veterans Affairs and are designed to help Veterans transition into homeownership with flexible terms and built-in protections.

Timing Your Home Purchase After Service

There is no one-size-fits-all timeline for buying a home after leaving the military. Some Veterans are ready to purchase immediately, while others benefit from waiting until civilian employment and income stabilize.

Important timing considerations include:

  • Length and stability of civilian employment

  • Whether relocation is likely in the near future

  • Comfort level with long-term commitments

  • Readiness to manage homeownership responsibilities

Taking time to evaluate these factors can prevent unnecessary stress later.

Evaluating Lifestyle and Housing Needs

Life after service often looks very different from military life. Veterans should consider how their housing needs may change as routines, family dynamics, and personal goals evolve.

Questions to ask include:

  • Is the location close to work, schools, or support networks?

  • Does the home fit current and future family needs?

  • Is maintenance manageable based on lifestyle and schedule?

  • Does the neighborhood support long-term plans?

Choosing the right home matters just as much as choosing the right loan.

Understanding Financial Readiness

VA loans offer flexibility, but Veterans should still evaluate their financial picture carefully. Budgeting beyond the monthly mortgage payment is essential.

Key financial factors to review:

  • Stable income and employment outlook

  • Emergency savings for unexpected expenses

  • Total housing costs, including taxes, insurance, and maintenance

  • Comfort with long-term financial commitments

Being financially prepared helps ensure homeownership remains a positive experience.

Using VA Benefits Strategically

VA loans offer advantages such as no down payment, no private mortgage insurance (PMI), and competitive interest rates. However, using the benefit wisely involves planning beyond the initial purchase.

Veterans should understand:

  • How VA entitlement works and can be reused

  • Long-term affordability, not just purchase price

  • Options for refinancing or future moves

  • How home equity fits into overall financial goals

Strategic use of VA benefits can support both short-term stability and long-term wealth building.

The Value of Professional Guidance

Veterans transitioning to civilian life benefit greatly from working with professionals who understand both VA loans and the unique challenges of military transitions. A VA-experienced Realtor and lender can help Veterans:

  • Determine readiness to buy

  • Evaluate housing options realistically

  • Navigate VA loan guidelines confidently

  • Avoid common mistakes during the transition period

Early guidance reduces uncertainty and builds confidence.

Final Takeaway

Buying a home after military service can be a powerful step toward stability and long-term financial growth—but only when approached thoughtfully. By evaluating lifestyle needs, employment stability, and future plans, Veterans can make informed decisions that support their goals.

With strategic use of VA benefits and experienced guidance, homeownership can become a strong foundation for life after service.

👉What’s My Property Worth? https://www.kimberlysutgroup.com/seller/homeestimate/default

📞 Call or text: (219) 789-1987
🌐 Visit our website: https://www.kimberlysutgroup.com
📘
Follow us on Facebook: https://www.facebook.com/Kimberlysutrealestate/

⭐ Read our 5-Star Google Reviews: https://g.page/r/CVNvGzCU3UZ3EBM/review


Kimberly Sut Group
Top Realtor for Buyers & Sellers in Northwest Indiana
Specializing in VA Homes, First-Time Home Buyers, Estate Sales & Relocations


Posted in Veterans VA
Oct. 9, 2026

Why VA Loan Experience Matters More Than the Interest Rate


When Veterans begin the homebuying process, interest rates often get the most attention—and while rates are important, they are not the most critical factor in a successful VA transaction. Experience with VA loans matters far more. VA loans follow specific guidelines, and mistakes made by inexperienced professionals can cost Veterans time, money, and even the opportunity to purchase a home.

VA loans are backed by the U.S. Department of Veterans Affairs and are designed to protect Veterans throughout the homebuying process. Those protections only work when the people handling the transaction understand how to apply them correctly.

VA Loans Are Not Conventional Loans

VA loans operate under different rules than conventional financing. These differences affect pricing strategies, appraisals, inspections, contract language, and closing timelines.

A VA-experienced Realtor understands:

  • VA appraisal standards and Minimum Property Requirements (MPRs)

  • How seller concessions work under VA guidelines

  • Proper contract structuring to remain VA-compliant

  • VA-specific timelines and documentation requirements

Without this knowledge, even small errors can cause delays or jeopardize the deal entirely.

Experience Protects Your VA Entitlement

VA entitlement is a powerful benefit earned through military service. Missteps—such as incorrect concessions, improper occupancy terms, or misunderstanding entitlement limits—can unintentionally affect a Veteran’s ability to use VA benefits in the future.

An experienced VA Realtor helps ensure:

  • Entitlement is used correctly

  • Long-term planning is considered, not just the current purchase

  • Veterans understand reuse and restoration options

  • No preventable mistakes compromise future buying power

Appraisals and Inspections Require Careful Guidance

VA appraisals and inspections are often misunderstood. They are designed to protect Veterans, but without experience, they can become points of confusion or conflict.

A VA-experienced Realtor:

  • Helps sellers prepare properties to meet VA standards

  • Advises buyers on realistic expectations before making offers

  • Navigates appraisal conditions without unnecessary alarm

  • Guides inspections with VA requirements in mind

This guidance keeps transactions moving smoothly.

Avoiding Costly Delays and Failed Contracts

Interest rates may fluctuate slightly, but a failed transaction can cost far more than a small difference in rate. Lost earnest money, extended housing costs, missed opportunities, and emotional stress often result from avoidable mistakes.

Experience helps prevent:

  • Poorly written offers that conflict with VA rules

  • Last-minute surprises at appraisal or underwriting

  • Communication breakdowns between agents and lenders

  • Deals falling apart due to misunderstandings

Why Experience Creates a Stronger Offer

In competitive markets, sellers want confidence. A VA-experienced Realtor knows how to present VA offers clearly, address concerns proactively, and educate listing agents so VA financing is viewed as a strength—not a risk.

Confidence and clarity often matter more to sellers than a fraction of a percentage point in interest rate.

Final Takeaway

Interest rates matter—but experience matters more. The right VA-experienced Realtor helps protect your entitlement, guide inspections and appraisals, and prevent avoidable delays that can derail a transaction.

For Veterans, success in homeownership isn’t just about the rate—it’s about working with professionals who understand the VA loan process and advocate for your best interests every step of the way.

👉What’s My Property Worth? https://www.kimberlysutgroup.com/seller/homeestimate/default

📞 Call or text: (219) 789-1987
🌐 Visit our website: https://www.kimberlysutgroup.com
📘
Follow us on Facebook: https://www.facebook.com/Kimberlysutrealestate/

⭐ Read our 5-Star Google Reviews: https://g.page/r/CVNvGzCU3UZ3EBM/review


Kimberly Sut Group
Top Realtor for Buyers & Sellers in Northwest Indiana
Specializing in VA Homes, First-Time Home Buyers, Estate Sales & Relocations


Posted in Veterans VA
Oct. 7, 2026

How Do You Prepare an Estate Property for Listing?

Preparing an estate property for listing doesn’t have to mean major repairs or renovations. In fact, most estate homes sell best with minimal preparation when the right steps are taken.

Understanding what matters—and what doesn’t—helps executors avoid wasted time and expense.

Start With Safety and Security

Before anything else, ensure the property is:

  • Secured (locks, doors, windows)

  • Insured properly for vacancy

  • Free of immediate hazards

Safety issues should always be addressed first to protect the estate and executor.

Remove Personal and Sensitive Items

Even if the home won’t be fully emptied, certain items should always be removed:

  • Personal documents

  • Medications

  • Valuables

  • Family keepsakes

This protects privacy and prevents loss.

Basic Clean-Up Goes a Long Way

You don’t need a full remodel. Simple steps often have the biggest impact:

  • Trash removal

  • Light cleaning

  • Clearing walkways

  • Basic yard maintenance

Cleanliness improves buyer perception without major cost.

Avoid Over-Improving

Executors often feel pressure to “fix everything.” In most estate sales:

  • Major updates don’t return full value

  • Renovations delay the sale

  • Repairs increase liability

Pricing correctly usually matters more than improvements.

Decide Whether to Sell Vacant or With Contents

Some estate homes sell best:

  • Vacant and clean

  • As-is with remaining contents

The decision should be based on market demand, buyer type, and timeline—not emotion.

Professional Photos and Accurate Marketing Matter

Even as-is estate homes benefit from:

  • Clear, honest descriptions

  • Professional photos

  • Accurate condition disclosure

Good marketing attracts the right buyers and reduces wasted showings.

Set Expectations Early

Buyers should understand:

  • The property is an estate sale

  • Repairs are limited or not offered

  • Timelines may differ from traditional sales

Clear expectations reduce renegotiation later.

Preparation Should Match Strategy

The level of preparation should align with:

  • Pricing

  • Buyer pool

  • Condition

  • Estate goals

Over-preparing or under-preparing can both hurt results.

Preparing an Estate Home to Sell?

If you’re unsure how much preparation your estate property really needs, understanding your options helps you move forward confidently.

👉What’s My Property Worth? https://www.kimberlysutgroup.com/seller/homeestimate/default

📞 Call or text: (219) 789-1987
🌐 Visit our website: https://www.kimberlysutgroup.com
📘
Follow us on Facebook: https://www.facebook.com/Kimberlysutrealestate/

⭐ Read our 5-Star Google Reviews: https://g.page/r/CVNvGzCU3UZ3EBM/review


Kimberly Sut Group
Top Realtor for Buyers & Sellers in Northwest Indiana
Specializing in VA Homes, First-Time Home Buyers, Estate Sales & Relocations

Posted in Estate Sales
Oct. 5, 2026

VA Loan Myths That Stop Veterans From Buying a Home


Many Veterans delay or avoid homeownership because of misinformation surrounding VA loans. Unfortunately, these myths often come from outdated experiences or from professionals who do not regularly work with VA financing. When handled correctly, VA loans are one of the most powerful and reliable home loan options available to Veterans.

VA loans are backed by the U.S. Department of Veterans Affairs and are designed to make homeownership more accessible—not more complicated.

Myth #1: VA Loans Take Longer to Close

One of the most common misconceptions is that VA loans take significantly longer to close than conventional loans. In reality, VA loans close on time every day when the transaction is managed by a VA-experienced lender and real estate team.

Delays are usually caused by:

  • Incomplete documentation

  • Poor communication

  • Lack of VA-specific knowledge

When professionals understand VA guidelines and timelines, closings are often just as fast as conventional loans.

Myth #2: VA Appraisals Are Harder to Pass

VA appraisals are frequently misunderstood. They are not designed to make transactions difficult—they are designed to protect Veterans by ensuring homes meet basic safety, livability, and value standards.

VA appraisals focus on:

  • Property safety and habitability

  • Accurate market value

  • Protecting Veterans from overpaying

With proper preparation and realistic expectations, VA appraisals rarely derail a well-structured transaction.

Myth #3: Sellers Won’t Accept VA Offers

Some Veterans believe sellers automatically reject VA offers. In truth, most sellers care about certainty, price, and timelines—not loan types.

VA offers become highly competitive when they include:

  • Strong pre-approval from a VA-experienced lender

  • Clean contract terms

  • Clear communication about VA financing

Educating sellers and listing agents eliminates hesitation and builds confidence.

Myth #4: VA Loans Come With High Fees

VA loans actually limit certain lender fees and allow sellers to contribute toward closing costs. Combined with no private mortgage insurance (PMI), VA loans are often more affordable than conventional options, both upfront and over time.

Some Veterans may also qualify for funding fee exemptions, further reducing costs.

Myth #5: VA Loans Are Only for First-Time Buyers

Many Veterans assume VA loans can only be used once or only by first-time buyers. In reality, VA benefits can often be reused, and partial entitlement may still allow another purchase—even without selling a current VA-financed home.

Understanding entitlement options opens doors many Veterans never realized were available.

Education and Experience Make the Difference

Most VA loan myths exist because of lack of education—not because of real limitations. When Veterans work with professionals who understand VA loans, these barriers disappear.

A VA-experienced team helps Veterans:

  • Separate fact from fiction

  • Structure strong, competitive offers

  • Avoid unnecessary delays

  • Move forward with confidence

Final Takeaway

VA loan myths should never stop Veterans from buying a home. With the right education, proper guidance, and experienced representation, VA loans are efficient, competitive, and powerful tools for homeownership.

The biggest obstacle is not the VA loan—it’s misinformation. Once that’s removed, Veterans can move forward with clarity and confidence.

👉What’s My Property Worth? https://www.kimberlysutgroup.com/seller/homeestimate/default

📞 Call or text: (219) 789-1987
🌐 Visit our website: https://www.kimberlysutgroup.com
📘
Follow us on Facebook: https://www.facebook.com/Kimberlysutrealestate/

⭐ Read our 5-Star Google Reviews: https://g.page/r/CVNvGzCU3UZ3EBM/review


Kimberly Sut Group
Top Realtor for Buyers & Sellers in Northwest Indiana
Specializing in VA Homes, First-Time Home Buyers, Estate Sales & Relocations


Posted in Veterans VA